Quarterly Hotel Update, as of December 2025 (Q4)
Executive Highlights
As seen from our regional aggregated hotel charts, 2025 reached record setting numbers for the region with three key measurements: Hotel Revenue, Average Daily Rate (ADR), and Revenue Per Available Room (RevPAR).
- Hotel Revenue: $440.6M, +2.0% vs 2024
- ADR: $180.19, +2.0 vs 2024
- RevPAR: $134.56, +0.6% vs 2024
However, Occupancy dipped slightly, down 1.1% vs 2024. Despite the year’s occupancy %, it was on par with the average level of demand for the region, at approximately 75% occupancy, and was still able to produce record high hotel rates, reflecting a willingness for guests to pay more than in 2024.
Q4 (October – December) 2025 Performance Highlights
Hotel room pricing in the region set a record high during this time of year too, with an increased ADR reaching $177 (+2.3% vs 2024). However, the demand (occupancy %) during this quarter was down by -2.6% (69.7% in Q4 2025 vs Q4 2024), indicating a softer late‑year demand (especially in Nov). Also, RevPAR and Revenue were both down slightly during this quarter vs the same period last year. RevPAR was -1.4% and Revenue was ‑1.3%.
The fourth quarter of the year is a transition time of the year for the region; the end of the peak-season with Fall Foliage (weather dependant of course) which then turns into a short shoulder-season, and the start of winter into the off-season for the majority of the region.
Here are the key numbers:
- Occupancy Rate:
- October: 79.5%
- November: 70.7%
- December: 58.7%
What this means: During the Fall Foliage, Hotels were almost 80%full in Oct (+0.5% increase over Sept 2025), before dropping 10% in Nov – indicating the end of the peak-season when businesses were still busy before the start of the shoulder-season in Nov. Though the shoulder-season sees less revenue, there are still opportunities to promote your products and services to visitors who might be more budget conscience (though with a high ADR, this might not be necessary). This is also a time of year for stakeholders to recover from a busy Q3 and plan for the off-season and year ahead. The dip in December to 58.7% is the lowest occupancy % of the entire year, representing a significant contrast to 2025’s peak in August with an occupancy of 86.6%.
- Revenue:
- October: $40.52 million
- November: $34.21 million
- December: $27.48 million
Why it matters: The hotel revenue over these three months really shows the impact of seasonality – though weather can play a key role here – it is an opportunity to ensure you still have products and services that you can offer to visitors in the region (maybe at a slightly lower cost than in August). If you don’t, please take advantage of the slower time to work on your business to grow, and the CCT staff can definitely assist you with generating ideas.
- ADR (Average Daily Rate):
- October: $186.52
- November: $178.14
- December: $166.66
Insight: Though Q4 is less busy than Q3, there are still opportunities to maintain price integrity as seen in ADR’s YoY growth in Oct 2025 (peak-season) AND Dec 2025 (off-season). As a reference, Q3 2025 vs Q3 2024 saw a YoY increase of +3-4% (+3.2% July 2025; +3.7% Aug 2025; and +3.5% Sep 2025). However, Oct 2025 vs Oct 2024 experienced a +5.5% YoY increase, and Dec 2025 vs Dec 2024 had a +4.4% YoY increase too (Nov 2025 ADR was -2.6% lower than Nov 2024). This indicates that the region’s strategic pricing allowed higher ADR growth (outpacing demand) while maintaining comparable occupancy percentages with 2024 and avoiding across-the-board price cuts. This allows opportunities to protect rates by diversifying products/services and adding value-addons (if possible).
- RevPAR (Revenue per Available Room):
- October: $148.36
- November: $125.95
- December: $97.91
Takeaway: Oct 2025, still in the peak-season, was the highest performing Oct in terms of Revenue, ADR and RevPAR in CCT’s reporting history; though it is also on the cusp of the shoulder-season and its pricing needs to be strategically balanced and flexible as weather plays a key role in these measurements (plus it is also unpredictable). For the rest of Q4, lower revenues per available rooms should be expected, as seen historically; however, consider Nov and Dec as opportunities to provide value add-on products and services to maximize revenues.
Key Insights for all Tourism Stakeholders
The final quarter of the year presents both opportunities and challenges for tourism stakeholders; as it wraps up the peak summer season, leading into a short shoulder-season (November) and begins the Winter season (often the off-season).
- Leveraging October Strength: October shows high occupancy (79.5%) and strong revenue ($40.5M). Stakeholders can further capitalize on this “post-peak-season/pre-shoulder-season” success by promoting Fall Foliage-themed experiences and possible Sports Tourism events and business conferences before the November slowdown.
- Rebuild shoulder‑season demand: Prioritize event programming and tailored campaigns for late Oct–mid Dec (e.g., festivals, culinary weeks, holiday markets) to smooth demand and lift occupancy without over‑discounting.
- Maintaining Yield over Volume: Since RevPAR and ADR are at historic highs, despite average occupancy levels, the focus should remain on attracting high-value visitors rather than simply increasing guest volume – this is a fine balancing act based on strategic pricing and diversifying products and services to align with demand.
- Stakeholder Investment: The consistent growth in total revenue (exceeding $440 M in 2025) provides a strong business case for continued investment in infrastructure and marketing to sustain high ADRs.
- Mitigating the “December Dip”: With occupancy falling below 60% in December, stakeholders should continue to develop targeted winter tourism products – such as festive events, holiday markets, or collaborate with other stakeholders to create “staycation” packages – to increase demand to explore the region and grow the visitor economy.
In closing…
2025 closed with record revenue on stable occupancy and strong hotel rates. The opportunity for 2026 is to add volume in late Q4 and maintain rate integrity, using targeted programming and value‑rich packages to keep RevPAR on an upward trajectory while supporting the broader visitor economy within the region.
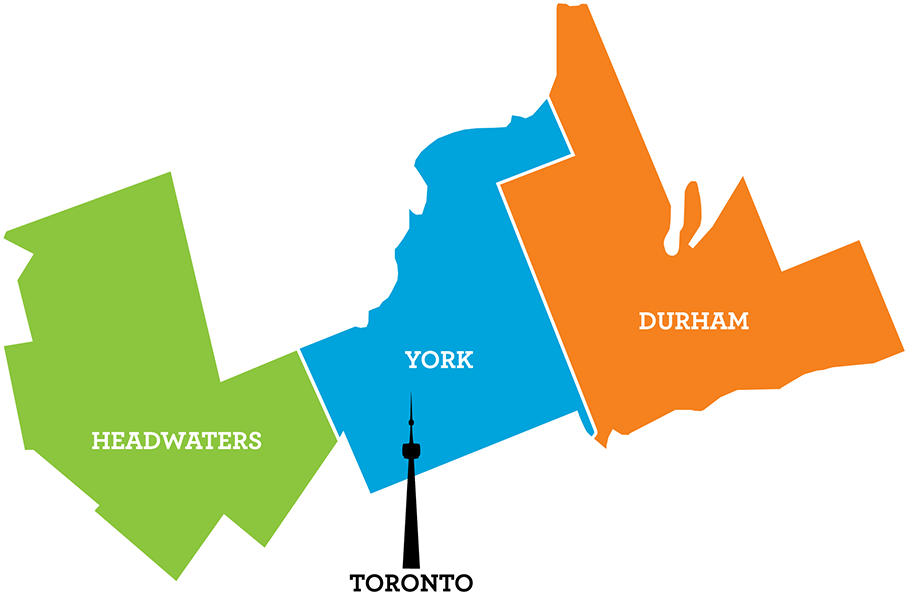
Click on the regional hotel reports below to see the Occupancy, Revenue, Average Daily Rate and Revenue Per Available Room for:
Please note: Daily & Weekly Occupancy % data for 2025 is also available, providing a more detailed view of demand patterns throughout the year. Check it out here.
For further assistance in identifying your target markets, please contact Tom Guerquin, Manager of Research & Development at Central Counties Tourism.
Central Counties Tourism collects aggregated quarterly hotel data from Co-Star for the available properties within our region, and each quarter, share those metrics with you.