Quarterly Hotel Update, as of March 2025 (Q1)
Central Counties Tourism collects aggregated quarterly hotel data from Smith Travel Research (STR) for the available properties within our region, and each quarter, share those metrics with you.
The first quarter of 2025 (January – March) provides insights into the performance of the hotel sector in Central Counties, reflecting underlying trends in tourism demand. Examining the key metrics – Occupancy, Revenue, Average Daily Rate (ADR), and Revenue Per Available Room (RevPAR) – Please take a look at the table first, especially Occupancy %.
Occupancy showed a clear upward trend across the quarter, starting at 60.3% in January, rising to 66.9% in February, and reaching 71.4% in March. The January – March 2025 average occupancy (Q1) was 66.2%.
Based on nine years of collecting hotel data for CCT, the first quarter of the year has historically been considered the least busy of the entire year (i.e. Jan being the lowest in occupancy %), and this trend continues in 2025. The 2025 Q1 average Hotel occupancy was slightly lower than 2024 Q1 (-2.4%), but when comparing the same period to 2019, the 2025 Q1 was slightly higher (+1.8).

Hotel occupancy (which shows us hotel demand) gradually grows toward the summer months, which tends to be the region’s busiest time of the year (peak season), and then declines after the fall season into the winter season.
Please Note: Though we will continue to look at the other metrics – Revenue, ADR and RevPAR – these three measurements are heavily impacted by inflation.
Revenue followed a similar positive trajectory month-on-month, generating $26,647,504 in January, $27,102,816 in February, and peaking at $33,560,879 in March. The Q1 total revenue for the quarter amounted to $87,311,199.
When comparing 2025 to 2024, the slightly lower occupancy (as shown above) is reflected on the revenue received (-1.4% in 2025 Q1). Though comparing revenue in 2025 to 2024 might be unfair as 2024 was an especially strong year for hotels in the region; however, when comparing 2025 to 2023, each month was 10-13% higher in 2025.

The Average Daily Rate (ADR) consistently increased throughout the quarter as well, from $159.16 in January, to $163.37 in February, and reaching $171.12 in March. The average ADR for 2025 Q1 was $164.55.
Though Occupancy and Revenue were both slightly lower in 2025 vs 2024, the ADR still continues to increase year-over-year. There could be various factors for this increase: inflation, market demand, a possible shift in the type of visitor (e.g., more business travel, luxury leisure), or successful yield management by hotels. Despite the 2.4% decrease in demand (occupancy %), hotel visitors were still willing to visit the region with a higher ADR.

RevPAR, a key indicator of hotel performance, also grew steadily, standing at $95.93 in January, increasing to $109.23 in February, and finishing the quarter at $122.16 in March. The average RevPAR for 2025 Q1 was $109.11.
Though the ADR increased, the RevPAR in 2025 Q1 had a -2.2 % less than the same time period in 2024.

For a tourism business operating within RTO6, these trends offer meaningful insights:
- Higher Visitor Spending Capacity: The increased ADR suggests that visitors staying in Central Counties hotels in 2025 Q1 were, on average, willing or able to spend more per night on accommodation. This could indicate a visitor demographic with a higher disposable income or a market willing to pay more for the perceived value.
- Opportunity Despite Lower Volume: Although occupancy was slightly lower than in 2023 and 2024, the increased revenue and ADR signal that focusing solely on volume (getting more heads in beds) might be less important than attracting visitors who contribute higher revenue per stay.
- Pricing Strategy Matters: The data supports the hotels’ ability to command higher prices. Tourism businesses should consider if their own pricing strategies align with this trend and explore opportunities to offer premium services or packages that cater to visitors willing to spend more.
In summary, 2025 Q1 shows a hotel sector in Central Counties characterized by robust pricing power and increased revenue compared to 2023, even with slightly lower occupancy than the two preceding years. For a tourism business, this highlights the potential of attracting and catering to visitors who are willing to spend more, rather than solely focusing on increasing visitor numbers.
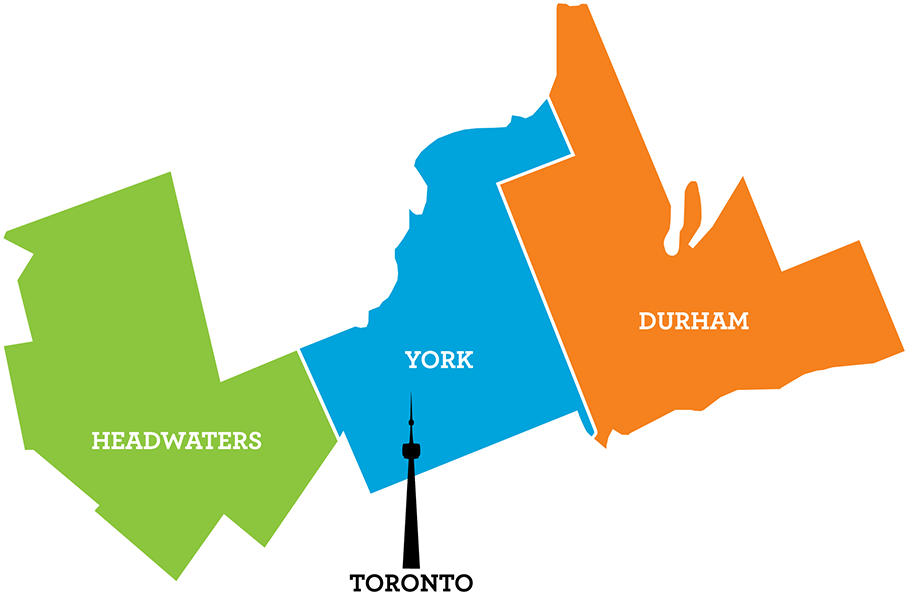
Click on the regional hotel reports below to see the Occupancy, Revenue, Average Daily Rate and Revenue Per Available Room for:
For further assistance in identifying your target markets, please contact Tom Guerquin, Manager of Research & Development at Central Counties Tourism.